
Divergence Alert Signals Between Memory ETF Implied Volatility and Industry Fundamentals
AI storage and computing power have pushed memory from a quiet subsector into the center of investor attention. DRAM, NAND, and especially HBM now anchor multi‑billion‑dollar ETFs and a growing ecosystem of options and index derivatives. As that ecosystem matures, implied volatility on memory ETFs has become one of the most watched gauges of risk and opportunity. But implied volatility is not the same thing as fundamentals. When memory ETF implied vol and industry fundamentals diverge, the difference is not just noise. It is an alert signal.
Sometimes implied volatility spikes while fundamentals remain stable. Other times fundamentals deteriorate while implied vol stays oddly calm. Both scenarios deserve attention. In a sector as cyclical and narrative‑driven as memory, divergence between market-implied risk and actual supply/demand, pricing, and capex conditions can reveal mispricings, crowded positions, and upcoming regime shifts in AI storage and computing power.
Implied Volatility vs Fundamentals: Two Different Lenses
Implied volatility (IV) on memory ETFs is derived from option prices. It represents the market’s expectation of future price movement, as expressed through demand for insurance (puts) and leveraged bets (calls). It is driven by:
- Investor sentiment and fear/greed cycles.
- Positioning in options markets and hedging flows.
- Macro factors and cross‑asset volatility.
Industry fundamentals, by contrast, are driven by:
- DRAM, NAND, and HBM pricing trends.
- Bit shipment growth and capacity expansion.
- Inventory levels, order books, and capex plans.
- AI workload growth, device demand, and storage architectures.
IV is a market lens; fundamentals are a business lens. Ideally, they point in roughly the same direction: rising IV when fundamentals worsen, falling IV when fundamentals improve. When they diverge, the market may be overreacting, underreacting, or pricing something fundamentals have not yet captured.
Types of Divergence to Watch
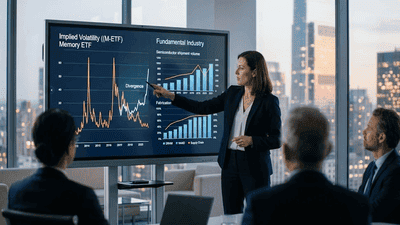
There are three primary divergence patterns between memory ETF implied volatility and industry fundamentals:
- High IV, stable fundamentals: Options market signals elevated risk, while fundamentals show steady pricing, controlled inventories, and readable demand.
- Low IV, deteriorating fundamentals: Options market appears complacent, while fundamentals point to rising inventories, softening prices, or cautious capex.
- High IV, improving fundamentals: Market still fearful, even as fundamentals show recovery—pricing stabilizes, bit growth resumes, inventories normalize.
Each pattern carries different implications for memory ETF investors and derivative users. The divergence itself is the alert: it tells you to look more closely rather than accept the market’s volatility signal as fully aligned with fundamentals.
High IV, Stable Fundamentals – Fear Without Fuel
In the first scenario, implied volatility on memory ETFs is elevated—options are pricing big moves—while industry fundamentals appear stable. There are several potential explanations:
- Macro or cross‑asset shocks: Broader market fear (rates, geopolitics) drives up volatility across sectors, including memory, without any specific chip cycle deterioration.
- Hedging waves: Large players hedge existing memory or AI hardware exposure with puts, pushing up IV even though they are not responding to new fundamentals.
- Short-term event risk: Upcoming earnings, policy announcements, or regulatory decisions lead to short-term IV spikes despite steady underlying conditions.
Here, divergence can signal opportunity. If you have conviction that memory fundamentals are intact—pricing flat or improving, inventories reasonable, AI storage demand solid—then high IV may offer attractive entry points for selling volatility (e.g., covered calls) or for buying memory exposure while options exaggerate perceived risk.
The alert signal is: the market is fearful, but fundamentals are not confirming that fear. Be cautious, but also ready to take advantage if your analysis supports it.
Low IV, Deteriorating Fundamentals – Complacency Risk
The opposite divergence is more dangerous: implied volatility is low, but industry fundamentals are weakening. DRAM or NAND prices start slipping, inventory builds up, and capex guidance turns cautious, yet memory ETF options do not reflect much concern.
Possible reasons include:
- Lagging market view: Options traders have not yet fully recognized or repriced the fundamental shift.
- Overreliance on AI narrative: Investors look at AI demand and assume memory risk is automatically covered, ignoring near-term cycle factors.
- Crowded positioning: Many participants are long memory/thematic exposure and reluctant to pay for protection, depressing IV in the short term.
This divergence is an alert that risk may be underestimated. Low IV makes protection cheaper, but it also suggests that a sharp reprice could come once fundamentals force the market’s hand. For memory ETF holders, this is a good time to consider buying puts or implementing collars, locking in protection while options remain relatively inexpensive.
The signal is: do not let low IV lull you into ignoring underlying cycle risk. Fundamentals may be flashing yellow while the options market is still green.
High IV, Improving Fundamentals – Recovery Mispriced
The third scenario occurs when IV is high but fundamentals show signs of recovery. Memory pricing stabilizes, inventories are worked down, and AI storage demand trends look healthier, yet the market continues to price big downside moves.
This can happen when:
- Past pain lingers: Investors burned in prior memory downturns remain wary and keep buying protection.
- News gap: Fundamental improvements are visible in specialized data but not yet widely recognized in broader market narratives.
- Macro volatility: External volatility keeps IV elevated even as industry-specific risk improves.
Here, divergence may indicate a mispriced recovery. If fundamentals continue to strengthen and the memory cycle is genuinely turning up, high IV could be an opportunity to acquire memory exposure at attractive risk premia or to sell expensive downside protection if you are willing to own the risk.
The alert is: the options market is stuck in a prior regime, while fundamentals suggest a new phase. Watch for alignment and consider positioning ahead of sentiment catching up.
How to Build Divergence Alerts in Practice
To use these signals systematically, you can build a divergence alert framework around memory ETFs and industry fundamentals. Practical components include:
- Implied volatility tracking: Monitor IV levels on memory ETF options, both absolute and relative to historical ranges.
- Fundamental indicators: Track DRAM/NAND/HBM pricing, inventory data, bit shipment growth, and capex guidance.
- Divergence metrics: Define thresholds for “IV high vs fundamentals stable/positive” and “IV low vs fundamentals negative.”
For example, you might flag alerts when:
- Memory ETF IV exceeds a certain percentile of its historical distribution, while pricing and inventories show neutral or positive trends.
- Memory ETF IV falls below a threshold, while pricing and inventory indicators worsen beyond defined limits.
These alerts do not automatically generate trades. They prompt deeper review and inform risk decisions—whether to hedge, adjust exposure, or exploit mispricing.
Using Index Derivatives to Act on Divergence
Index derivatives on memory and AI hardware indices—futures and options—are natural tools for acting on divergence alerts. Some ways to translate signals into strategies:
- High IV, strong fundamentals: Consider selling puts or implementing put spreads on the memory ETF or index, or writing covered calls, to harvest rich premiums while holding underlying exposure.
- Low IV, weak fundamentals: Consider buying protective puts on memory ETFs or indices, or using collars to cap downside, locking in cheap insurance ahead of potential repricing.
- High IV, improving fundamentals: If you expect recovery, consider buying calls or call spreads, or reducing hedge intensity, anticipating IV normalization and price recovery.
These derivative strategies are not speculative by default; they can be used to align portfolio risk with actual cycle conditions, rather than with raw market fear or complacency.
Integrating Divergence Alerts into AI Storage/Compute Portfolios
In a broader AI storage and computing power portfolio, divergence alerts should inform how you balance memory and compute exposure and how you manage risk:
- Memory sleeve management: Use IV–fundamental divergence to adjust memory ETF weights and hedges, rather than purely following price trends.
- Compute vs memory balance: If memory fundamentals deteriorate while IV stays low, you might tilt more toward compute or equipment until the cycle stabilizes.
- Cross-asset risk: High IV driven by macro shocks may call for broader risk reductions, not just memory-specific adjustments.
In this sense, divergence alerts become part of a multi-sleeve risk dashboard, not an isolated signal. They help you avoid overreacting to volatility divorced from fundamentals and underreacting to fundamental shifts masked by calm options markets.
Common Pitfalls When Interpreting Divergence
Several pitfalls can arise when reading IV–fundamental divergence:
- Over-trusting short-term data: Fundamentals can be noisy; one month of pricing or inventory data does not define a cycle.
- Ignoring cross-asset contagion: High IV may reflect global volatility, not memory-specific issues; low IV may reflect stable macro rather than stable memory fundamentals.
- Confusing regime shifts with mispricing: Sometimes divergence persists because a real structural change has occurred, not because the market is wrong.
The antidote is to view divergence as a prompt for deeper analysis, not as a trading signal in isolation. Before acting, check multiple fundamental series, cross-check IV against other sectors, and assess whether you are witnessing a cyclical wobble or the early stages of a new regime.
Why This Matters More in the AI Era
In the AI era, memory is no longer just another cyclical component. It is central to AI infrastructure performance, and its cycles can amplify or dampen the pace of AI deployment. Memory ETFs and index derivatives have become key tools for expressing AI storage views. As their use grows, implied volatility on these instruments will increasingly reflect dynamic interplay between AI narrative, cycle fundamentals, and global risk conditions.
Divergence between memory ETF IV and industry fundamentals is therefore more than a technical curiosity. It is a window into how markets are perceiving and misperceiving memory’s role in AI. By paying attention to these divergence alerts, investors can better calibrate their AI hardware exposure, hedge more intelligently, and avoid being caught off guard when volatility and fundamentals finally align in unexpected ways.
The memory wall may be a technical bottleneck, but the way we interpret risk around it—the balance between implied volatility and fundamentals—is just as important in shaping investment outcomes.
You May Like

Narrowing Spread Between NAND Spot and Contract Prices in 2026 – A Signal
By 2026, one of the most watched metrics in the NAND flash market has started to shift in a subtle but meaningful way: the spread between spot prices and long‑term contract prices is narrowing. For casual observers, this may look like just another incremental change in a notoriously volatile industry. For memory makers, module houses, device OEMs, and data center buyers, however, a tightening gap between spot and contract prices is a signal—a reflection of evolving supply–demand balance, risk perceptions, and strategic behavior on both sides of the market.

Price Divergence Trading Strategies Between NAND Flash and DRAM ETFs
NAND flash and DRAM sit at the core of AI storage and computing power. Both are memory, but they are not the same business. DRAM is main memory—fast, volatile, and central to high‑bandwidth workloads like AI training and inference. NAND is non‑volatile storage—slower than DRAM, but crucial to persistent data and large‑scale object storage. The cycles that drive their pricing and margins overlap, yet they often diverge. That divergence is where trading strategies between NAND and DRAM ETFs become interesting.

China’s HBM Localization Progress: The Catch-Up Pace of CXMT and XMC
China’s drive to localize advanced memory technologies has accelerated over the past several years. High-Bandwidth Memory (HBM) sits near the center of that strategy because it is integral to AI accelerators, high-performance computing (HPC) and other strategic compute platforms. Two domestic players—ChangXin Memory Technologies (CXMT) and XMC (Xianghui Memory, commonly referred to as XMC)—have become focal points in assessing how quickly China can close the gap with international incumbents on HBM die, stacking, and packaging.

Thermal Simulation Challenges and Solutions in 3DIC AI Chip Design
As AI workloads push chips to deliver ever higher compute density, designers are increasingly turning to three‑dimensional integration (3DIC) to stack dies vertically and pack more functionality into limited footprints. While 3DIC architectures unlock significant performance and bandwidth advantages, they also introduce complex thermal behaviors that are far harder to predict and manage than in traditional 2D layouts.

An Attempt at Compiling a Memory+Compute Fusion Thematic Index – A Dual-Track Framework
Most AI investors talk about “compute” as if it were the whole story: GPUs, accelerators, chips, cores. But every one of those cores needs somewhere to read from and write to. Memory and storage define how wide the data highway really is. In practice, AI performance is a fusion of compute and memory, not a solo act. So why do so many indices and ETFs separate them into different silos—one for semiconductors, one for memory, one for data centers—when the actual workloads keep blending them?

Surging Demand for Laser Drilling and Plasma Dicing Equipment in Advanced Packaging
Advanced packaging has become one of the semiconductor industry’s most important growth engines, and it is now pulling a surprising set of process tools into the spotlight. Among the most in-demand are laser drilling and plasma dicing equipment. These machines sit close to the heart of heterogeneous integration, fan-out packaging, wafer thinning, TSV formation, glass substrate processing, and other advanced flows where precision, yield, and throughput matter enormously. As packaging moves from a back-end afterthought to a strategic platform, the equipment used to shape, open, and separate materials has become just as important as the dies themselves.

D2D Interface Bandwidth and Latency Comparison in Chiplet Architectures
Chiplet architecture has turned the package into a real performance battleground. Once multiple dies are placed side by side or stacked within the same advanced package, the quality of the die-to-die, or D2D, interface becomes one of the most important determinants of system behavior. Bandwidth is no longer a nice-to-have metric, and latency is no longer a small implementation detail. Together, they shape whether a chiplet system feels nearly monolithic or frustratingly fragmented.

Stock Selection Logic and Alpha Validation of ESG-Themed Semi ETFs
Semiconductor themed ETFs are no longer just about growth and cycles. A growing subset now layers environmental, social, and governance (ESG) criteria on top of traditional sector exposure. These ESG semi ETFs promise two things at once: access to one of the market’s most powerful secular themes, and alignment with sustainability and governance standards. The pitch is appealing, but it raises two hard questions. First, how exactly are these stocks being selected? Second, does the ESG overlay help, hurt, or leave alpha unchanged?